

The cost of a weak R&D pipeline may be causing the nation to miss opportunities, undercapitalise on innovation, and slow its national progress, according to Daniel Salas, Policy & Projects Officer at Engineers Australia.
Engineers are indispensable to Australian research and development (R&D). Almost one-third of the engineering workforce is employed in R&D-intensive sectors such as manufacturing or professional, scientific and technical services. Of Australia’s total business spend on R&D, half is engineering-related.
With the Australian Government’s Strategic Examination of R&D (SERD) aiming to harness existing strengths and maximise current investment, now is a timely moment to assess the current landscape and explore how engineers can continue to advance the national interest.
Billion-dollar challenge
Discussion about Australia’s R&D capabilities often returns to the same contrast: our strength in discovery research versus our persistent struggles in commercialisation.
It is well documented that Australia excels in research, producing 3.4 per cent of the world’s published output, despite only representing 0.33 per cent of the global population.¹ In the face of this achievement, we still struggle commercialising these ideas.
The World Intellectual Property Organisation’s 2025 Global Innovation Index ranks Australia 16th for innovation inputs (up two places) but only 27th for outputs (up three places).¹
This challenge is hardly new. Engineers Australia’s 2022 Commercialisation of Engineering Innovation highlighted the same weakness, echoing findings from the Department of Industry, Science & Resources and Group of Eight universities.² The consensus is clear: the innovation pipeline is underpowered. The cost is missed opportunities, undercapitalised ideas and a growing sense that we are falling behind.
Across government, industry and the professions, calls are mounting to address Australia’s decline in R&D investment. Gross expenditure on R&D (GERD) sits at just 1.68 per cent of GDP, a steady decline from its 2.24 per cent high in 2009, and well below the OECD average of 2.7 per cent. With both spending declining, and persistent challenges in commercialising innovations, many argue we should aim for at least 3 per cent.
Government direct funding and tax support for business R&D, 2023 (as a percentage of GDP)

Doing so would require an additional $23.1 billion annually. With a tight commonwealth budget, much of this $20-plus billion gap will need to come from the private sector.
Australia’s push to lift R&D intensity is further complicated by its reliance on just three industry divisions – professional, scientific and technical services; manufacturing; and financial and insurance services – which account for nearly 73 per cent of total R&D investment.¹⁰ The SERD discussion paper notes that global manufacturing intensity and R&D intensity are closely correlated. Australia’s business R&D intensity is less than half that of peer countries, and manufacturing contributes only 6 per cent of industry Gross Value Added compared to 17 per cent in comparator nations.³ In this context, much of policymakers’ hope rests on a comparatively smaller industrial base than those of peer economies.
Business R&D by industry sector

Approaches to addressing these challenges differ. The Australian Industry Group cautions that additional funding alone may not improve outcomes without addressing structural weaknesses, while the Australian Academy of Science proposes an R&D levy to force all business to review their commitment to R&D.⁶
Strategic response
Recognising the importance of lifting R&D intensity and reversing steady declines in expenditure, in December 2024 the government convened an independent expert panel to review Australia’s R&D system. Chaired by Tesla and Blackbird Ventures chair Robyn Denholm, the panel also includes former Chief Scientist Ian Chubb, surgeon and researcher Professor Fiona Wood AM, and LaunchVic CEO Dr Kate Cornick.
In February 2025, the panel opened public consultations in response to its discussion paper. Engineers Australia’s submission touched on refining our commercialisation skills pipeline, businesses’ access to R&D incentives and support, and improving government procurement.
Through September 2025, six thematic papers were released. They covered the panel’s overarching objectives of maximising investment value, strengthening linkages, supporting national priorities, increased R&D investment, and ultimately uplifting Australia’s R&D intensity and performance.
The SERD Panel is expected to deliver its final report of recommendations in December.
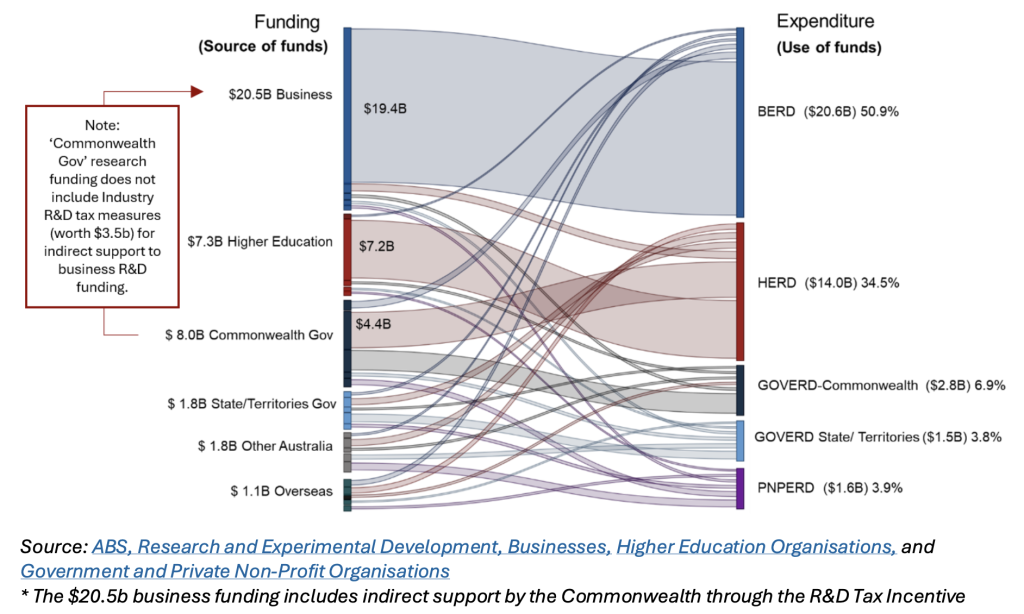
R&D flows from funding source to performer (2021-22)
Navigating the streams
The Australian R&D ecosystem is marred by a system of funding sources often acknowledged as unnecessarily complex. The first issues paper released by the SERD acknowledges this challenge and notes the likely inefficiencies and duplications that would arise amongst Australia’s 215 individual R&D funding streams.
The message in these issues papers is clear: Australia’s R&D support system may not be fit for purpose, or coordinated sufficiently. Reform is needed to better reflect the structure of our economy and better support SMEs to scale their innovations.
Scaling up
A central challenge in reaching the 3 per cent GERD may lie in the structure of Australia’s economy with a small share of manufacturing, fewer middle-sized companies and the government’s financial support settings.
Our economy is dominated by microbusinesses, with 94 per cent of firms employing between one and nine people. In countries such as Germany, Canada and the United States, the share is far lower – around 62-67 per cent.⁵ SMEs are also responsible for 55 per cent of overall business expenditure in R&D.
The Australian Government’s financial support is heavily skewed towards Research and Development Tax Incentive (RDTI), which accounts for around four-fifths of all government support for business R&D – compared to 57 per cent in the OECD average.⁶ In 2021–22, small businesses made up 38 per cent of RDTI claimants but received only around 20 per cent of the $11.2 billion in incentives.
Through our consultations, we learned that many SMEs choose to bypass the RDTI altogether, citing the RDTI’s compliance burden, limited benefits, and delayed returns as barriers.⁷
Finding the balance
An R&D system more fit-for-purpose for SMEs – and businesses more broadly – requires a sharper balance between discovery and commercialisation. Policy must clearly distinguish between research and development, and between discovery and commercialisation activity. Engineers are central to the development phase of R&D, yet government policy often treats the two as interchangeable, with limited attention given to commercialisation.
The task, then, is not to diminish the value of discovery, but to strike a more balanced approach. Aligning funding with the structural needs of our economy – and our recognised gaps in commercialisation – could help ensure Australia’s research strengths translate into real-world innovation and economic returns.
Bridging the gap
Beyond structural and market barriers, a deeper question arises: does Australia have the skills base to meet its R&D challenges? As mentioned, the process of commercialisation – turning discovery into products and processes – relies heavily on engineering thought and practice.
As Biomedical College Chair Dr Kelly Coverdale CPEng put it during consultations for the SERD: “In research and development, the ‘development’ is the process of fundamental engineering design and testing. Engineers are the key ingredient in development,” she said. “Policymakers often treat research and development as the same, but the processes differ.
“Research is primarily scientific in process, while product development is inherently an engineering practice.”
This perspective highlights a crucial point: boosting R&D investment is not enough without the absorptive capacity to translate funding into outcomes. That means sustained investment in the engineering workforce across research AND development.
Global and local trends point to growing skills pressures.
Australia’s skills challenge is ever present. The Australian Industry Group notes 37.5 per cent of businesses using science and mathematics skills cannot find qualified staff – the second-highest reported shortage in the country.⁸ Engineers Australia’s submissions to the SERD similarly underscored the need to grow skilled human capital if the process is to deliver meaningful reform and called for more attention to be provided to the development and refinement of “commercialisation” skillsets amongst our graduates. Our submission in response to the SERD issues papers recommended increased government support for work-integrated learning to help engineering students build these broader capabilities.
As global competition for engineering talent intensifies and international R&D investment accelerates, Australia faces a pressing question: how can we attract and retain top-level engineers when our own R&D performance is in decline?
The global trends, in addition to those in Australia, raise hard questions for the viability of our engineering skills pipeline under current settings. Are we building our sovereign capability and producing enough skilled graduates to insulate ourselves from fluctuations in the global talent market and to turn our ideas and innovations into national prosperity and growth?
Discover cutting-edge research and innovation, and the latest breakthroughs in applied mechanics at the 12th Australasian Congress on Applied Mechanics.
References
¹ Department of Industry, Science and Resources. Australia’s National Science Statement: A Future Made in Australia. 12 August 2024. https://www.industry.gov.au/publications/national-science-statement-2024.
² World Intellectual Property Organization (WIPO). Global Innovation Index 2024. World Intellectual Property Organization, 2024. https://www.wipo.int/en/web/global-innovation-index.
³ https://www.industry.gov.au/publications/barriers-collaboration-and-commercialisation, https://go8.edu.au/go8-response-to-the-university-research-commercialisation-consultation-paper, https://www.youtube.com/watch?v=ZILe-8lPF7U
⁴ SERD discussion papers figure 17 & 18 – Comparator nations are Canada, Germany, Japan, South Korea, Sweden the United States
⁵ Australian Industry Group, Understanding Australia’s declining R&D performance, 2023, https://www.aigroup.com.au/resourcecentre/research-economics/economics-intelligence/2023/understanding-australias-declining-rd-performance/
⁶ Industry Innovation and Science Australia. Barriers to Collaboration and Commercialisation. Department of Industry, Science and Resources, 27 November 2023. https://www.industry.gov.au/publications/barriers-collaboration-and-commercialisation
⁷ https://www.oecd.org/en/topics/sub-issues/rd-tax-incentives.html 2023 numbers
⁸ AI Group
⁹ Australian Industry Group. Understanding Australia’s Declining R&D Performance. Research Note, 2023. https://www.aigroup.com.au/resourcecentre/research-economics/economics-intelligence/2023/understanding-australias-declining-rd-performance/