
Although semiconductors have a place on the federal government’s List of Critical Technologies in the National Interest, Australia’s contribution to the sector is modest. What can be done to change this?
Semiconductors are a technology crucial for enabling our modern data and device-driven lives.
Reports in recent years describe them as “a critical component in all modern technologies”, “a structural growth engine powering the next era of global innovation”, and “a global engine for technology, economic and social progress”. Deloitte predicts that the current generative AI boom will account for half of chip sales this year, totalling $US 1 trillion.
There are four broad types of semiconductor: logic (for information processing), memory (information storage), application-specific integrated circuits (ASICs, which carry out one routine) and system-on-a-chip (SoC or integrator chips).
Australia produces no microchips of any kind in significant volumes. The nation’s contribution to the now – mostly silicon – semiconductor world is slight, notes a July paper by the Semiconductor Sector Service Bureau (S3B).
According to Deloitte Access Economics research for S3B, this represents $955 million in revenue and supports 5,790 full-time equivalent jobs directly and indirectly. It comprises about 180 organisations, largely “startups, SMEs and university-linked ventures”.
That contribution is modest by international standards, Matthew Worsman, S3B’s Acting Director, told create.
“But it has real capabilities in R&D, small-scale innovative companies, and, at the other side with applications and semiconductor-enabled technologies,” he said.
What exists is “concentrated in research, design, application-specific engineering, and early-stage development rather than large-scale production” according to the Deloitte paper.
“We have proven capabilities in quantum-enabled systems, photonics, photovoltaics – where Australia’s a world leader – [and] compound semiconductors around like gallium nitride and silicon carbide, where Australia has capabilities,” Worsman said.
Three sites in Australia are in “commercial low volume” production, by S3B’s count.
A laser focus
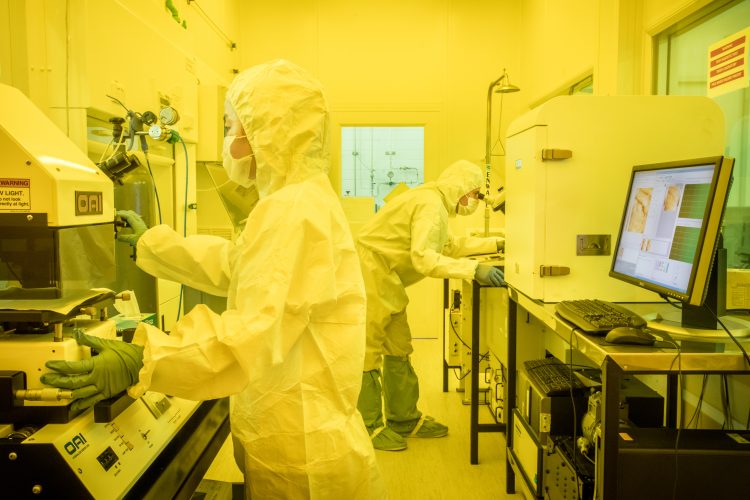
One of those sites is at the Silverwater, NSW, HQ for ASX-listed company BluGlass. Founded in 2006, BluGlass was based on a remote plasma chemical vapour deposition process developed at Macquarie University.
After several strategic shifts, from equipment sales to licensing, the company has evolved into a fully integrated device manufacturer focused on the high value, low volume niche of visible-wavelength gallium nitride lasers.
“While our patents and publications are critical, our real intellectual capital sits within our people. Gallium nitride is a complex, frontier semiconductor material system, and the expertise needed to engineer it at commercial scale comes from leveraging over a decade of hands-on problem-solving, ” said Dr Ian Mann, the company’s Chief Technology and Operations Officer.
“So there’s a core team of five or six of us that have been here for a very, very long time.”
The core team’s expertise and the company’s core process are anchored to their Australian site. As part of its shift in business model, BluGlass acquired a fabrication facility in Silicon Valley in 2022, and also – further downstream – runs a packaging and test site at New Hampshire.
The newness of gallium nitride as a laser material and lack of commercial manufacturing meant that outsourcing downstream processing and packaging of laser chips to contract manufacturers gave poor results, so this was brought inhouse: an uncommon example of an Australian company needing to own production end-to-end.
“[This] allowed us to vertically integrate and control our supply chain, from growing our unique devices atom-by-atom in Sydney to producing the laser systems ready for customer integration in the United States,” added Mann.
“Instead of capturing only wafer-level revenue, we can now deliver high-value finished products, as well as customise the device to meet our customers’ exacting needs. That ability to commercialise the full value of the devices we grow here in Australia is a major differentiator.”

Making microchips can be awesomely complex, and the expertise involved has helped drive extreme specialisation and globalisation. An advanced chip can take over 1,000 processing steps to create, and might have 100 or more layers. Niches abound along the way.
“You can’t dominate the entire supply chain. This is too complex. Even a country like Taiwan will rely on specialty gases and specialty liquids from around the world,” said Worsman.
As mentioned in a 2019 Accenture report, a semiconductor device crosses as many as 70 international borders on its way to a customer.
READ: Future proofing data centres for surging AI workloads
Targeted tech
Niches for the technology are also emerging within the nascent quantum computing genre, which has a slew of problems to address before reaching widespread adoption.
US-Australian company Lumina Corp has targeted integrated photonics, which co-founder Dr George Li said is following a similar path to the integrated electronic era, “15 years ago or 20 years ago, when things were moving from discrete components … into a chip.”
The company’s thin film lithium tantalate-based tech has attracted interest from quantum companies, which have significant issues around footprint, including with control channels.
“It’s what we like to call the quantum wiring problem, and it’s basically each qubit needs one, two, three, four, five different channels of different-coloured light. And you’re trying to get all this light into a very small amount of space – a 3D volume,” explained Li.
“But you have to use just a lens that takes up 3D volume, and so you physically only get them so close. So that means if you want to have more qubits, the size of your setup just explodes.”
Companies are connecting up to hundreds of qubits, translating to 100 m2 or so worth of equipment, mostly in free-space optics, said Li.
Lumina was founded in 2023 based on co-founder Dr Keith Powell’s post-doctoral research, and was cash positive last year. “Ninety-nine per cent” of demand comes from quantum computing businesses, said Li.
“I think that’s a no-brainer that basically solves that bird’s nest wiring problem, and [does] multiple channels on a 2D-scaling solution as opposed to this 3D volumetric [one],” he said of the problem.
Barriers to growth?
Anthony Christian has spent more than 35 years in the industry, first in manufacturing with Philips Semiconductors in the UK, and later via about 15 years in research environments, including as Facility Manager at the Queensland node of the Australian National Fabrication Facility.
He founded and heads the Queensland Semiconductor Initiative and the new Semiconductor Industry Association of Australia.
Christian sees an opportunity establishing a nation-first “flexible, short-run semiconductor foundry capable of serving defence, critical infrastructure, advanced manufacturing, photonics and emerging technology sectors”.
“Most global foundries are optimised for very high production volumes,” he said.
“There is a significant gap for companies that need prototype devices, pilot production, specialised processes or secure manufacturing.”
Christian believes Australia needs a long-term strategy, as well as facilities for prototyping, validation and manufacture, more skilled people, and “much closer collaboration between government, universities and industry”.
S3B agrees that the issue is multi-faceted and long-term. It is currently researching what it says is Australia’s first roadmap, scheduled for an October release and looking as far as 15 years ahead.
Their discussion paper, kicking off the consultation process, identified a self-reinforcing skills gap: industry needs talent and vice versa. Opportunities are limited for “hands-on experience in process development, fabrication, packaging, testing and system integration.”
Companies scaling up face a “missing middle” separating research and early-stage innovation from industrial scale and everything that comes with it.
Then there’s the limited local supply of familiarity, patience and investment money, with the “combination of capital access, supply chain access and market proximity” encouraging growing startups to pack their bags.
READ: From AI to bioengineering, pay attention to these tech trends
Bang for buck
Mann says that when it comes to making chips, emerging, small-volume applications where there’s a high technical challenge but a less-high capital cost are a possibility. Particularly in compound semiconductors.
“When you look at BluGlass and Silanna together, Australia has something genuinely unique: two of the world’s leaders in low-temperature gallium nitride deposition (the manufacture of the semiconductor material), which opens up novel devices outside of the capabilities of traditional deposition techniques, Mann offered.
“There are enormous opportunities across the compound-semiconductor landscape. I’m a GaN person, of course, but the same frontier potential exists in indium phosphide, gallium arsenide, silicon carbide, and other material systems.
“Each brings its own strengths, and together they open a wide spectrum of next-generation devices and applications that don’t require the multi-billion-dollar fabs of silicon semiconductors.”
Government assistance and orders have been crucial to industry development, from the early days of Silicon Valley to the world champion in contract manufacture, Taiwan’s TSMC.
Is this the answer for Australia? An Australian Strategic Policy Institute paper in 2022 advocated $1.5 billion in investments and incentives to establish distributed, public-private funded compound semiconductor fabrication plants, followed by those in “trailing edge” – mature process – silicon complementary metal–oxide–semiconductors (CMOS).
Building any kind of fabrication plant requires nuanced discussion, given the diversity of technologies classed under semiconductors, said Worstman.
“So the question is: what is the commercial reason that Australia should invest in a facility like that, particularly with access to markets, the necessary people, the necessary capital, the necessary infrastructure?” he said.
He added that Australia can be “a trusted partner in a global network and that’s where I think Australia should position itself”.
When create spoke to Li, Lumina had just fabbed for the first time in Australia, at University of Sydney, and was about to kick off a capital raise “to stand up a wafer-scale pilot”. A long-term goal is a full foundry in Australia.
He also advocated nuance, explaining that CMOS logic chips were often connoted when semiconductors were mentioned. However, even among very different photonics chips, there exists a world of diversity that could get confusing for any non-expert.
With high-value applications requiring small volumes and processes nowhere near those of advanced logic chips – maybe 40 nm as compared to 3 nm, a local fabrication plant could stack up, believes Li.
He added that establishing the “first and only photonics foundry in Australia” was a three-to-four-year plan, and that now was an opportune moment.
“For CMOS, that ship’s long since sailed,” he said. “So for photonics, the next five years is the time to jump on this train if you don’t want to miss it.
“And if you miss it in five years, it’s going to be gone.”
Register now for the upcoming Information, Telecommunications and Electronics Engineering Symposium