
Australia was tipped to lead the global green steel revolution, backed by abundant iron ore and renewable energy. In 2026, the technology is progressing, but at a slower and more fragmented pace than many expected.
Just a few years ago, green steel felt like Australia’s next great industrial opportunity.
When create examined the sector in 2024, hydrogen-based steelmaking was gaining momentum globally, governments were announcing major funding packages and Australia appeared to hold all the right cards: vast iron ore reserves, abundant renewable energy resources and strong international trade relationships.
Two years later, the tone has shifted.
A recent report from independent think tank Climate Energy Finance described Australia’s progress on green iron and steel as “sporadic”, and highlighted the risk of Australia losing its window of opportunity to become a global leader in this space.
“While Australia is yet to see a final investment decision for a single commercial-scale lower-emission iron proposal, the Middle East and North Africa are advancing proposals at pace with lower fossil energy costs, high renewable energy resources, streamlined approvals and development timelines, and active state capital support,” said report author Matt Pollard, CEF net-zero transformation analyst.
“Industry now requires a stepchange in speed of execution, coordination across all levels of government, and the political will to back Australia’s first movers before competing nations and regions can leverage learning curves and economies of scale in the low-carbon economy and lock down offtake relationships that Australia had the opportunity to secure.”
So, how does that assessment compare with what is actually happening in industry, and is Australia really being left behind?
What’s actually happening on the ground?
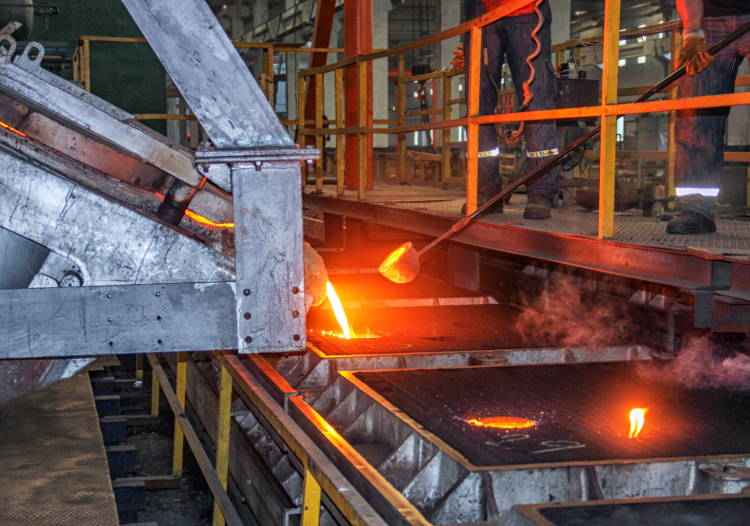
The process of replacing existing steelmaking infrastructure with greener alternatives has moved slower than many in Australia hoped.
Blast furnaces remain the dominant steelmaking technology globally. They can produce between 1000 and 15,000 t of pig iron per day, and are built to operate continuously for decades, making them difficult and expensive to replace.
But, around the world, companies are now testing different ways to gradually reduce emissions while keeping steel production running, said Associate Professor Tom Honeyands, Co-Director of the BHP Centre for Sustainable Steelmaking Research at the University of Newcastle.
“There definitely has been progress internationally,” he told create. “There’s a group called Stegra in Sweden which is the poster child for this, and they are building a green hydrogen DRI plant with an electric arc furnace.”
This plant is due to be operating commercially by 2030.
Meanwhile, in China, steel giant Baowu is testing ways to reduce emissions from its existing steelmaking equipment by injecting hydrogen into its blast furnaces and recycling gases that would normally be wasted back into the process.
South Korean steelmaker POSCO has also broken ground on its HyREX demonstration plant, which is testing a new way of making iron using hydrogen and electricity.
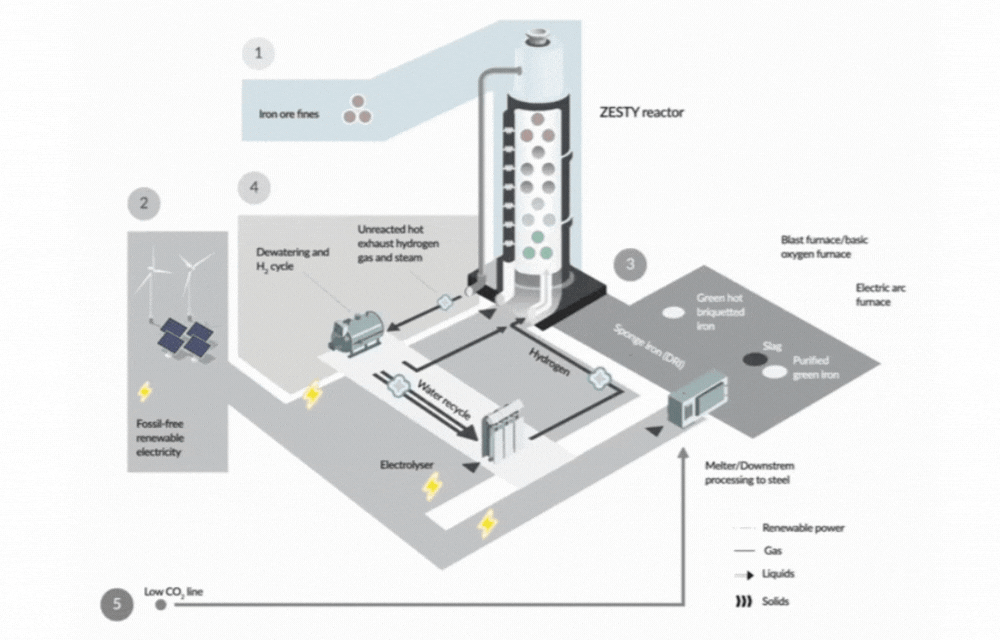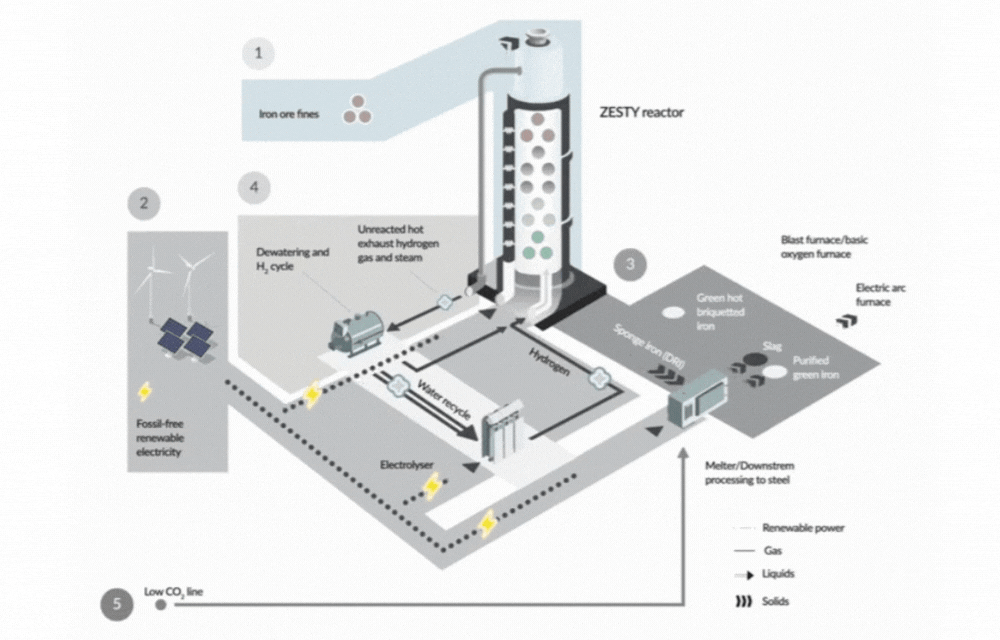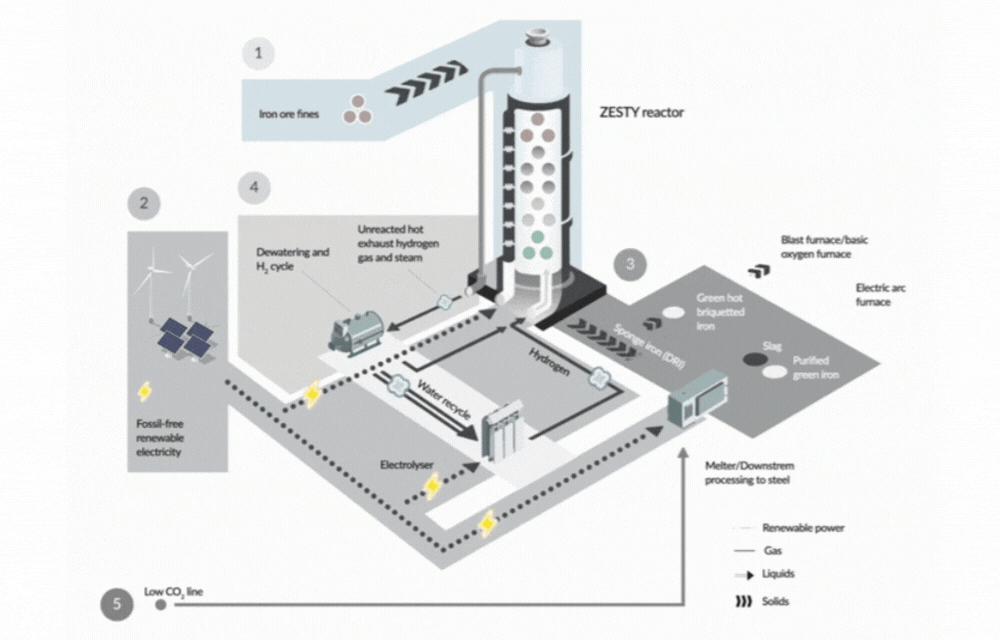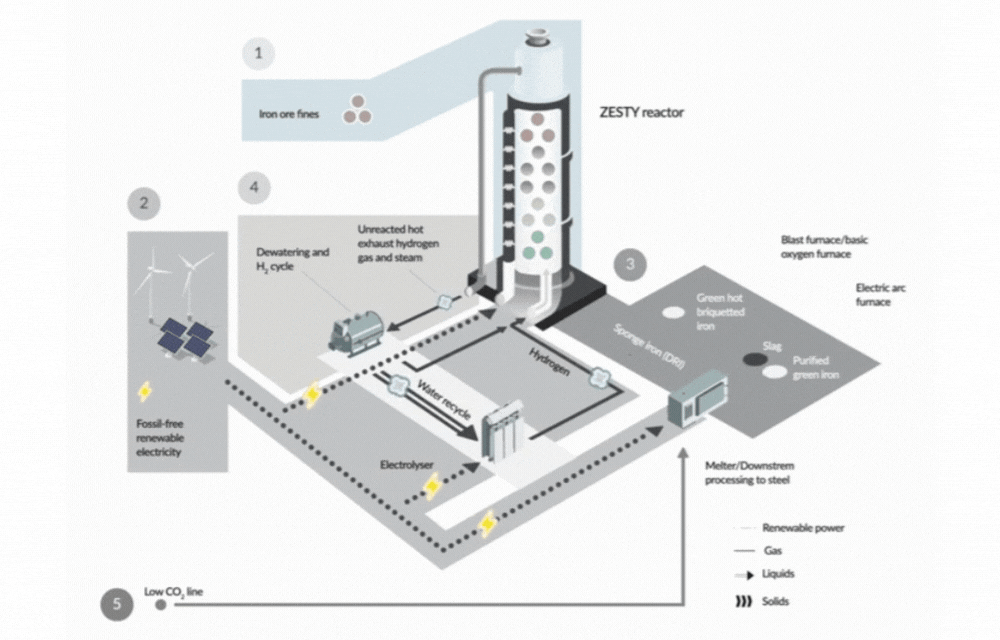
The process first uses hydrogen to remove oxygen from iron ore in a fluidised bed reactor, where fine ore is kept suspended in a flowing gas so it reacts evenly. The resulting iron is then fed into an electric smelting furnace, which uses electricity to melt it into liquid iron for steelmaking.
That last technology is particularly significant for Australia, Honeyands said.
“We export 900 million t of iron ore annually, and it’s all around 62 per cent iron or less, which isn’t good enough for the electric arc furnace if you’re making direct reduced iron. But it’s perfect for an electric smelting furnace.”
The fluidised bed system also allows fine iron ore to be used directly, avoiding some of the extra processing steps required in conventional systems.
“Most of all the existing DRI processes need pellets, which means you need to grind the ore up, pelletise it, then heat it to 1300°C – so it’s more energy-intensive.”

That shift towards electric smelting has become one of the biggest areas of activity for Australian industry.
Honeyands’s team at the University of Newcastle is already collaborating with POSCO on laboratory-scale hydrogen reduction and electric smelting research.
They are also contributing to NeoSmelt – a joint venture involving BHP, Rio Tinto, BlueScope Steel, Mitsubishi Corporation and Woodside Energy – which is planning a demonstration electric smelting furnace in Kwinana, Western Australia.
“You’ve got the big miners and steelmakers in Australia working on that, so they clearly all see its potential as a replacement for the blast furnace in the future,” he said.
Why the transition is harder than expected
One of the biggest shifts since 2024 has been a growing recognition of just how difficult large-scale hydrogen production will be.
“People have definitely gotten less enthusiastic about hydrogen,” Honeyands said.
While hydrogen is still central to long-term decarbonisation plans, producing enough green hydrogen to support global steelmaking requires staggering amounts of renewable electricity, he explained.
Rather than waiting for fully green hydrogen systems to become viable, many companies are now looking at transitional approaches that can reduce emissions sooner and adapt over time.
“For example, you can start one of these processes up using reformed natural gas, and then transition more and more hydrogen into it as it becomes available,” he said.
Another challenge is replacing existing infrastructure without disrupting steel production.
“In Australia, steel mills have one blast furnace each, and that blast furnace has got to operate. But some of the ones in China have 10. So you could quite happily knock one down every year for the next 10 years and build an electric arc furnace in its place.”
These challenges have reframed the shift towards green steel. Rather than striving for an overnight transition to hydrogen solutions, companies are instead looking at ways to progressively lower emissions while existing plants continue operating.
Simon Koger, Climate Change Manager at Engineers Australia, pointed to a recent webinar by the Institute for Energy Economics and Financial Analysis as a good primer for why the cost of DRI with natural gas for lower emissions steel production is generally unviable at the global level.
“Of particular note is the context that Australia’s biggest export industry (iron ore) is a potential risk for China, due to our political ties to the US,” Koger said.
“It could be argued that value-adding our iron ore by decarbonising the iron ore supply chain out of Australia could go a long way to alleviating that geopolitical risk – in addition to providing a product more easily accessible to European markets through the Carbon Border Adjustment Method (CBAM), which was introduced January 2026.”
What the future could look like
Looking ahead, Honeyands foresees different regions adopting localised pathways to low-emissions steelmaking.
“There’s not one magic solution,” he said. “It depends a lot on what iron ore you have, what types of steel you’re making and the local conditions in terms of renewable electricity.
“If you’ve got lots of sunlight or wind, you can start to add hydrogen into the system.”
While smaller-scale approaches such as electrolysis or alternative smelting methods may not replace blast furnaces outright, they could play a role in specific contexts.
“In regions where you don’t have the huge centralised steel mill, you could have a smaller one which makes 100,000 t a year using those technologies and supports local industry.”
As more buildings, vehicles and infrastructure reach the end of their lifespan, larger volumes of scrap steel are expected to enter the market. But making greater use of scrap steel will also require more sophisticated recycling and sorting systems.
“If you just keep recycling things – for example, you just get a whole car, crush it up and melt it – you start getting these residual elements building up, and the steel quality deteriorates,” he explained.
With several technological pathways developing at different speeds, Honeyands remains optimistic about the overall direction of the industry.
“I would hope that in the future, there will be a lot of slightly different bespoke solutions around the world, which allow them to decrease emissions significantly from where they are now.”
Koger said that while progress has been slow in recent years due to expense and longevity driven challenges associated with existing methods, there is the potential to:
- Underpin Australia’s energy security in the coming decades
- Safeguard Australia’s primary export industry through value adding its local supply chain, making the product more attractive on the global market
- Stabilise geopolitical relations with China in a manner that facilitates its own export opportunities with the EU and other countries that introduce a CBAM
“Australia needs greater introduction of value-added iron ore,” he said. “There will be a substantial need for this going forward.”
EVENT: Witness innovation in structural engineering at Australasian Structural Engineering Conference.